Digital Ticketing and Tourism Revenue Accountability
Cashless tourism payments can improve transaction traceability, but digital payment alone does not guarantee that every visit is recorded, every receipt is reconciled, or every failure is detected. Gunungkidul's Baron pilot shows why control design and measurable evidence matter.
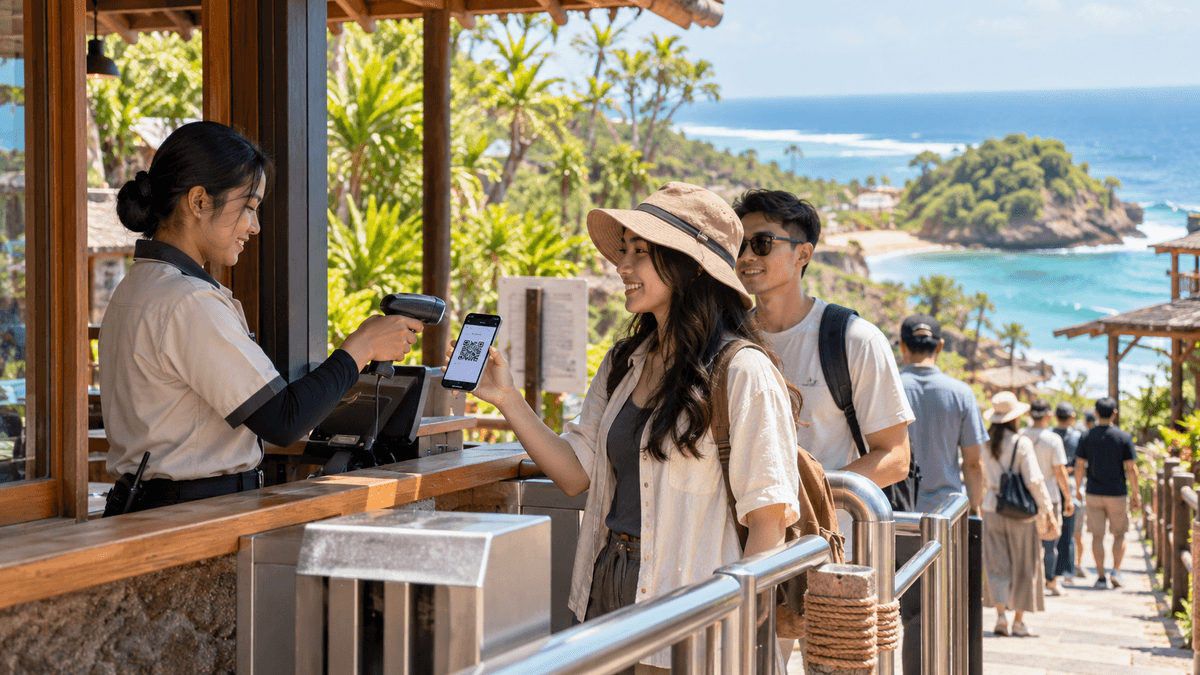
Cashless payment changes the control environment
Moving a tourism-retribution collection point from cash to digital payment changes how money is transferred and recorded. It can reduce the handling of cash and create electronic records, but the payment method alone does not prove that every eligible visitor paid, every payment produced a valid entry record, or every transaction reached the correct government account.
For Gunungkidul Regency, the relevant policy question is whether the complete chain, from visitor entry to payment settlement and public accounting, can be reconstructed, reconciled, and independently checked. A digital system may improve control, but only when the data and procedures around it work as one process.
This is a narrower question than measuring all tourism revenue leakage or building a public tourism dashboard. The focus here is transaction control at official tourism-retribution collection points.
What has been publicly documented in Gunungkidul
In March 2026, the local tourism office described a roadmap for cashless payment at tourism-retribution posts and named Baron as the pilot location. The roadmap discussion identified equipment, internet connectivity, and electricity as implementation requirements. (Gunungkidul Tourism Office, March 31, 2026 (opens in a new tab))
The tourism office reported that a trial conducted from April 6 to 11 found more than 80% readiness to use noncash payment among the people and visitors consulted. The page describes the result as a readiness measure; it does not provide the sampling details needed to interpret it as a representative estimate for all visitors or all collection points. The local government then announced the launch of a 100% cashless tourism-retribution system at Baron Utama on May 12, 2026. (Gunungkidul Tourism Office, May 13, 2026 (opens in a new tab); Gunungkidul Regency Government, May 12, 2026 (opens in a new tab))
A later government report stated that revenue at the Baron pilot point had increased 159% year over year and that the share of noncash transactions in total regional revenue had risen from 10.60% to 35.81%. It also acknowledged unstable internet, electricity interruptions, and differences in user readiness. The report does not give enough detail about the comparison period, transaction-level counts, or a comparison site to establish that cashless payment caused the reported revenue increase. These figures should be treated as the government's reported results, not an independently verified impact evaluation. (Gunungkidul Regency Government, digital-transformation report (opens in a new tab))
Five control questions that matter more than the payment device
1. Does each payment correspond to a valid entry record?
A reliable system should connect an entry or vehicle record to the applicable tariff, the payment attempt, the final transaction status, and the receipt or validation signal used by gate staff. If payment and entry records sit in separate systems, reconciliation must use stable identifiers and rules that prevent one payment from being counted twice or an entry from being treated as paid without evidence.
The system should also record legitimate exceptions, such as authorized exemptions, refunds, canceled entries, or approved adjustments. Without these records, a variance can be difficult to interpret: it may indicate a control failure, a legitimate transaction exception, or a data-matching problem.
2. Can the day's collections be reconciled?
At the end of each operating day, the collection team should be able to compare the number of chargeable entries, the total amount due under the applicable tariff, payment-provider records, settlement into the government-controlled account, and accounting entries. The process should produce a documented explanation for every material difference.
Reconciliation should not mean that totals merely look similar. The team needs to know whether differences come from settlement timing, transaction failures, refunds, tariff categories, missing entry records, manual overrides, or incorrect posting. Each exception should have an owner, resolution status, and time stamp.
3. Can operations continue safely when the network or electricity fails?
The tourism office has identified connectivity and electricity as practical concerns in cashless implementation. A control design should therefore specify what staff may do during an outage, how a pending transaction is distinguished from a failed or completed payment, how visitor access is handled, and how the system is reconciled after recovery.
The contingency procedure should be approved by the responsible finance authority and should preserve an auditable record. Staff should not improvise unofficial collection methods or treat an unclear payment status as confirmed. The aim is service continuity without creating an undocumented route around the control system.
4. Can visitors use the system without avoidable exclusion?
A cashless gate still needs clear instructions, visible support, and a practical process for visitors who have limited connectivity, an incompatible device, insufficient digital-payment access, or trouble completing a transaction. Digital inclusion is an operating requirement for a public service that keeps electronic records.
If the policy requires cashless payment at a location, the operator should publish an authorized assistance and contingency procedure that does not undermine the legal basis or audit trail. Visitor complaints, failed-payment incidents, and queue delays should be reviewed alongside collection results.
5. Can an independent reviewer reconstruct a transaction?
An auditor should be able to select a sample and follow each transaction from the gate or entry record to payment confirmation, provider settlement, accounting, and any refund or adjustment. Access permissions and change logs should make unauthorized edits visible. The system should retain the record needed to investigate discrepancies without unnecessarily exposing visitor personal information.
Electronic records can improve auditability, but only when identifiers, access controls, retention practices, and exception logs are designed for review. A digital receipt is evidence of a transaction; it is not by itself evidence that the entire collection process is complete and correct.
How to measure whether the pilot is working
The evaluation should compare defined periods before and after implementation, using daily data where possible and stating the exact dates. A similar collection point that has not yet changed systems can provide useful context, although differences in location, tariffs, traffic, season, and operating practices must be considered before it is used as a comparison group.
A concise operational scorecard should include:
- Transaction coverage: chargeable entries matched to valid payment or documented exception records.
- Reconciliation quality: value and number of unmatched items, the age of unresolved differences, and the proportion resolved within the target period.
- Payment reliability: completed, failed, canceled, reversed, and pending transactions; payment-system uptime; and recorded network or electricity outages.
- Service quality: queue time, time to resolve failed payments, and visitor complaints related to payment or entry.
- Control exceptions: manual overrides, refunds, voids, duplicate records, and changes made after the day-end close.
- Financial settlement: the amount recorded in the collection system compared with provider settlement and the relevant government account.
The scorecard should disclose definitions and denominators. For example, a high share of noncash payments does not show whether every eligible entry has been captured. Likewise, a rise in total receipts should be interpreted alongside visitor volumes, tariff changes, operating days, and seasonality.
Scale only after controls and service have been tested
The published record establishes Baron as the pilot location and describes an ambition to expand cashless collection. The public material reviewed for this article does not provide a complete, current implementation register for every tourism-retribution post. It is therefore not appropriate to state how many sites currently operate under the system without checking the latest official register.
Before expansion, the regency should document the minimum operating standard for each new site: network and power readiness, equipment and training, tariff configuration, payment-provider setup, reconciliation ownership, outage procedures, privacy controls, and independent review. A site should not be considered ready solely because a payment device has been installed.
A phased expansion also permits comparison across operational conditions. If a site has unreliable connectivity or weak support capacity, the response should be a funded readiness plan rather than a blanket assumption that digitalization will deliver the same result everywhere.
Conclusion
Digital ticketing can strengthen tourism-retribution accountability by improving transaction traceability and reducing reliance on manual cash handling. It cannot guarantee accountability without a control chain that links entry, payment, settlement, accounting, and exception resolution.
For Gunungkidul, the next step is to publish the pilot's measurement definitions and matched-period results, including transaction reconciliation and service reliability. The government-reported revenue increase is a reason to evaluate the system carefully, not a substitute for that evaluation. Expansion should follow verified control performance, reliable visitor service, and an auditable record.
Sources consulted
- Gunungkidul Tourism Office. “Rapat Tentang Roadmap Cashless Pembayaran Pos Retribusi” [Meeting on the Cashless Payment Roadmap for Retribution Posts]. Published March 31, 2026. https://wisata.gunungkidulkab.go.id/rapat-tentang-roadmap-cashless-pembayaran-pos-retribusi/ (opens in a new tab). Checked October 26, 2026. Documents the pilot roadmap and infrastructure requirements.
- Gunungkidul Tourism Office. “TPR Baron Sebagai Pilot Project Pembayaran Non Tunai (Cashless)” [Baron Retribution Post as the Noncash Payment Pilot]. Published May 13, 2026. https://wisata.gunungkidulkab.go.id/tpr-baron-sebagai-pilot-project-pembayaran-non-tunai-cashless/ (opens in a new tab). Checked October 26, 2026. Reports the April trial and the office's stated readiness result.
- Gunungkidul Regency Government. “Gunungkidul Resmi Luncurkan Retribusi Wisata 100% Cashless di TPR Baron Utama guna Tingkatkan Transparansi dan PAD” [Gunungkidul Launches 100% Cashless Tourism Retribution at Baron Utama]. Published May 12, 2026. https://gunungkidulkab.go.id/gunungkidul-resmi-luncurkan-retribusi-wisata-100-cashless-di-tpr-baron-utama-guna-tingkatkan-transparansi-dan-pad/ (opens in a new tab). Checked October 26, 2026. Confirms launch announcement and stated policy rationale.
- Gunungkidul Regency Government. “Gunungkidul Akselerasi Transformasi Digital, Indeks ETPD Capai 97% dan PAD Sektor Pariwisata Melonjak” [Gunungkidul Accelerates Digital Transformation as the ETPD Index Reaches 97% and Tourism PAD Rises]. Publication date not identified on the opened page. https://gunungkidulkab.go.id/gunungkidul-akselerasi-transformasi-digital-indeks-etpd-capai-97-dan-pad-sektor-pariwisata-melonjak/ (opens in a new tab). Checked October 26, 2026. Attributed source for the 159% year-over-year claim and stated operational constraints; not an independent causal evaluation.
Keep reading
This article is part 2 of 6 in the series "Tourism Revenue and Accountability".
- Previous: Gunungkidul Tourism Revenue: What the 2025-2026 Reports Show
- Start of the series: Gunungkidul Tourism Revenue: What the 2025-2026 Reports Show
Related articles: